 Today · Echonomia Post
1. Marvell Plotting a Massive Lumentum Buy? In the artificial intelligence (AI) race, whoever controls the bottleneck calls the shots; and they’ll pay whatever price it takes to get it.
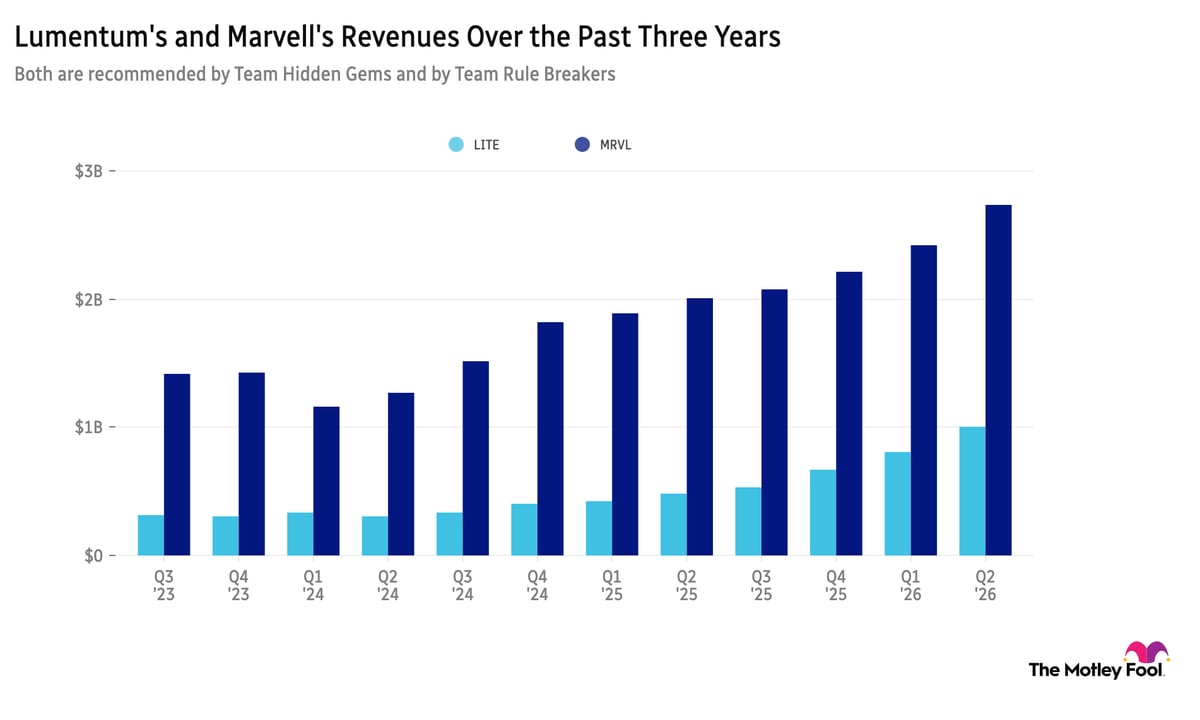
Marvell ( MRVL +3.32% ) is reportedly in advanced talks to acquire Lumentum ( LITE +5.51% ) , according to Bloomberg. Nothing is official, but the report says a deal could be announced within the next few days. Lumentum shares were up over 4% in early trading today after closing 5.5% higher on Wednesday.
Marvell stock was down around 10% in pre-market trading today. The rationale : AI clusters are swapping copper wires for light (optics) to connect chips, and optics supply is tight. Lumentum, which makes the lasers and photonic circuits that connect GPUs inside AI data centers, is fully booked for AI components through 2029.
Marvell can directly control the lasers needed to connect AI chips if it acquires Lumentum. Why the stock divergence: Lumentum is worth about $83 billion now, more than one third of Marvell’s market cap. An acquisition this big would mean a heavy stock sale, debt, or both.
It’s also an expensive bet – Lumentum is expected to generate a little over $4.5 billion in revenue in fiscal year 2027. Whether this merger happens or falls apart, one thing is clear: optics is evolving as a critical AI bottleneck, and those who own it should win. 2. Alphabet Stock Slumps 10%, But Why?
Alphabet ( GOOG +1.60% ) slumped more than 10% in early trading, even though its third-quarter revenue rose 24.7% year over year to $127.6 billion. The real star? Google Cloud – its revenue jumped 103% to $30.7 billion as businesses scrambled to rent AI compute power and grab Google's custom TPU chips.
Cash burn, and the stock’s fall: Operating income rose nearly 30% to $40.6 billion, but earnings per share still fell 26% because of an $8.7 billion loss on equity investment holdings. Growth also came at a cost. Free cash flow swung to negative $9.1 billion from positive $24.6 billion a year earlier.
Capital expenditures of $51.4 billion were nearly 40% of revenue. Management gave no formal guidance. Spending fears resurface: Cloud growth has accelerated for six straight quarters, but the market runs on fear.
As Fool contributing analyst Matt Frankel noted, “With capex expected to rise “significantly” next year, fears about the financial side of the AI build-out seem to be overshadowing the impressive cloud growth.” 3. Earnings Roundup: Why Some Stocks Got Hammered Revenue growth didn’t shield two of our recommendations this morning, and the details below show why. Fortinet ( FTNT -5.90% ) fell more than 25% in pre-market trading.
Third-quarter revenue rose 20% to around $2.1 billion. The global cybersecurity company, however, guided for roughly 15% growth at the midpoint for Q4. Even so, Fortinet is still 100% ahead of the S&P 500 since its 2024 Hidden Gems recommendation.
ServiceNow ( NOW -3.00% ) , a Team Hidden Gems recommendation, fell 19% this morning. Q3 revenue rose to $4.1 billion, but the enterprise software company’s AI deployment costs hit profits. Its professional services segment reported a gross loss of $23 million.
Microsoft ( MSFT -0.06% ) posted double-digit revenue growth for the quarter ended Sept. 30. Capital spending, the money it puts into data centers and servers, surged. Scaling AI training runs increases data center power consumption and requires billions in upfront server investment.
The stock was up 4% this morning. Sterling Infrastructure ( STRL +5.82% ) , a Team Hidden Gems rec, more than doubled Q3 revenue to $1.6 billion. Large-scale site development accelerated, pushed by data center and semiconductor demand.
The stock dipped 2% pre-market. Chipotle ( CMG +2.68% ) , recommended by Team Hidden Gems and by Team Rule Breakers, rose 7% after Q3 revenue climbed 9.6% year over year. Net income fell 11.1%. 4.
Fool Recs Reporting, Each With a Test to Pass Six recs from across TMF services report earnings, five after today’s close and one tomorrow morning. Amazon ( AMZN +0.59% ) rents out computing power through AWS alongside its online store. Cloud growth and data center spend are the numbers to size up.
Intel ( INTC +1.91% ) wants to manufacture chips for other companies too. New customers for its factory business would show the turnaround has traction. Roblox ( RBLX -2.19% ) runs a platform where players spend time in games other users build.
Rising time and spending per player would show the audience is still deepening. Starbucks ( SBUX +0.15% ) is mid-turnaround and trying to win customers back to its U.S. coffee shops. Growing store traffic would show the proof it’s working.
Gilead Sciences ( GILD +0.07% ) makes the HIV medicines that anchor its sales. Early demand for its newer HIV-prevention shot is the upside to watch for. Chevron ( CVX +0.43% ) reports before the market opens tomorrow.
Oil and gas production, plus the cash it returns to shareholders, will show how well it’s holding up. 5. Instacart Is the Top Dog DoorDash Wants Team Rule Breakers This week, we saw reports that DoorDash ( DASH -0.63% ) was in talks to acquire Maplebear ( CART -2.76% ) , owner of Instacart. Neither party has confirmed the talks.
Still, the reports show what being a Top Dog is worth. One Rule Breaker trait we look for is market dominance: being the Top Dog in an important, emerging industry. Team Rule Breakers recommends Maplebear.
Instacart dominates U.S. grocery delivery: its share may be as high as 68% of the intermediary market (third-party websites). That figure drops significantly when we include retailers’ own websites. DoorDash, a Team Hidden Gems recommendation, is the clear Top Dog in U.S. restaurant delivery, with about 67% market share.
Team HG's November 2023 Stock Advisor recommendation is up 94%, beating the S&P 500 by over 8%. DoorDash faces a choice. Option 1 is to keep growing slowly: DoorDash adds grocery partners, accepting a back-seat role while the retail partner owns the customer relationship.
Instacart is lying in wait to take over those partnerships if DoorDash messes up or pushes too hard on pricing. Option 2 is to buy the Top Dog: That makes DoorDash number one while removing a rival that might undermine its growth-by-partnership plan. In business, you’d much rather be fighting from a position of strength and dominance.
Instacart holds that position in grocery. Even the Top Dog next door appears to prefer buying it over fighting it. 6. Today’s Question!
What investment mistake still haunts you, and what did you learn from it? Discuss with friends and family, or become a member to hear what your fellow Fools are saying! The Motley Fool has positions in and recommends Alphabet, Amazon, Chevron, Chipotle Mexican Grill, DoorDash, Fortinet, Gilead Sciences, Intel, Lumentum, Marvell Technology, Microsoft, Roblox, ServiceNow, Starbucks, and Sterling Infrastructure.
The Motley Fool recommends Instacart and recommends the following options: short December 2026 $38 calls on Chipotle Mexican Grill. The Motley Fool has a disclosure policy . Pre-market price and change as of 5am Eastern, versus previous day’s futures settle price for indexes and previous pre-market price for Bitcoin.
Source: The Motley Fool